During the week of 12 May 2025, European Council President António Costa will travel to the Western Balkans to meet with the political leadership and co-host the sixth European Political Community Summit in Tirana. Source link
Gaza: UN agencies reject Israeli plan to use aid as ‘bait’
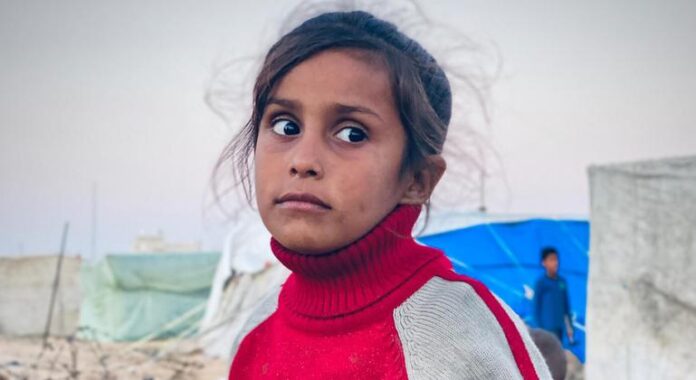
UN Children’s Fund (UNICEF) spokesperson James Elder insisted that the Israeli proposal to create a handful of aid hubs exclusively in the south of the Strip would create an “impossible choice between displacement and death”.
The plan “contravenes basic humanitarian principles” and appears designed to “reinforce control over life-sustaining items as a pressure tactic”, he told journalists in Geneva. “It’s dangerous to ask civilians to go into militarized zones to collect rations…humanitarian aid should never be used as a bargaining chip”.
The Gaza Strip has been under a complete aid blockade for more than two months and humanitarians have warned repeatedly that food, water, medicines and fuel have been running out.
Kids and elderly at risk
If the Israeli plan were to happen, Gaza’s most vulnerable individuals – the elderly, children with disabilities, the sick and the wounded who cannot travel to designated distribution zones – would face “horrendous challenges” retrieving aid, the UNICEF spokesperson maintained.
The Israeli aid distribution blueprint presented to UN humanitarians envisages only 60 aid trucks per day entering Gaza – “one-tenth of what was being delivered during the ceasefire” between Israel and Hamas which held from 19 January to 18 March.
“It’s not nearly enough to meet the needs of 1.1 million children, 2.1 million people,” Mr. Elder insisted. “There is a simple alternative: lift the blockade, let humanitarian aid in, save lives.”
Thousands of trucks in limbo
Stressing the success of the UN-led aid scale up during the ceasefire, humanitarian affairs coordination office spokesperson Jens Laerke urged the Israeli authorities to “facilitate the aid that we and our partners have available just a few kilometres away” just outside Gaza.
UNRWA, the largest aid provider in the Strip, said that the UN agency has “over 3,000 trucks of aid” that are stuck outside Gaza.
Juliette Touma, Director of Communications, deplored the fact that such a “big dollar figure” was going to waste, when the food could be reaching hungry children and when medicine could be used to treat people with chronic diseases.
“The clock is ticking. The gates must reopen, the siege must be lifted as soon as possible,” she insisted, while calling for the release of Israeli hostages and a return to a standard flow of humanitarian supplies.
Inside Gaza, aid teams warn that the situation is desperate. “Even those [food] lines are now gone because food is running out,” said UNRWA’s Ms. Touma.
Nothing left to queue for
In an update on Thursday, OCHA said that more than 80 community kitchens have been forced to shut since late April, owing to the lack of supplies. This number is rising “by the day”, fuelling “widespread” hunger in Gaza, the UN aid coordination office said.
Rebutting Israeli allegations that aid reaching Gaza has been diverted by militant groups, both Ms. Touma and UN World Health Organization (WHO) spokesperson Dr. Margaret Harris described “end-to-end” systems put in place to counter this risk.
“Our supplies are reaching the health facilities they’re meant to serve,” said Dr. Harris, adding that the UN health agency had not witnessed any aid diversion within the health care system.
“It is not about failure of aid delivery within Gaza. It is about not being allowed to bring it in,” Dr. Harris concluded.
In a further note of caution about the Israeli plan, UNICEF’s Mr. Elder insisted that the proposed use of facial recognition as a precondition to access aid ran against all humanitarian principles to “screen and monitor beneficiaries for intelligence and military purposes”.
He recalled that the ceasefire earlier this year had resulted in a “huge” improvement in children’s nutrition.
“It meant food in the markets, repaired water systems…It meant people could access health care safely. It meant health care facilitators had medicines that they need.”
‘Boastful’ denials of aid
Fast forward to today and food, water, medicines – “everything for a child to survive” – is being blocked, Mr. Elder said — “and in many ways, boastfully blocked”.
The UNICEF spokesperson also expressed concern that the Israeli plan risks separating family members “while they move back and forth to try and get aid” from the designated locations in a territory that “lacks any safety” amid ongoing bombardments.

Keeping a steady hand in an unsteady world

Speech by Isabel Schnabel, Member of the Executive Board of the ECB, at Hoover Monetary Policy Conference “Finishing the Job and New Challenges”, Stanford University
Stanford, 10 May 2025
Standard theory of monetary policy rests on a simple premise: a stable relationship between inflation and the output gap. This is the logic behind the Phillips curve, which, in its most common form, relates inflation to a measure of economic slack, expected inflation and supply shocks.[1]
The relationship between output and inflation was already under scrutiny well before the pandemic.
After the global financial crisis of 2008, inflation didn’t fall nearly as much as had been implied by conventional Phillips curve estimates. And once economies around the world recovered and unemployment fell, the bounce-back in inflation fell short of model predictions.
This is why that episode is known as the period of “missing deflation” and “missing inflation”.[2]
The situation changed fundamentally in the aftermath of the pandemic, when the relationship between inflation and the output gap proved to be much stronger than what would have been expected based on historical estimates. We observed a noticeably steeper Phillips curve across advanced economies, including the euro area (Slide 2).[3]
In my remarks today, I would like to draw lessons from the instability of the Phillips curve over the past 20 years for the optimal conduct of monetary policy. I will argue that the evidence of a re-flattening of the Phillips curve after the long period of high inflation suggests that, in the euro area, the most appropriate policy response to the potential risks to price stability arising from fiscal expansion and protectionism is to keep a steady hand and maintain rates close to where they are today – that is, firmly in neutral territory.
Monetary policy and the slope of the Phillips curve
The slope of the Phillips curve has first-order implications for the conduct of monetary policy.
If the curve is steep, as it appeared to be in recent years, monetary policy is highly effective in reducing inflation, with only a limited impact on growth and employment. The smaller “sacrifice ratio” suggests that central banks should react more forcefully to deviations of inflation from target, even when the economy is hit by a supply shock that pushes inflation up and output down.[4]
A steep Phillips curve hence improves the trade-off facing central banks, weakening the case for “looking through”, as forceful policy action minimises the risks of inflation expectations unanchoring and of inflation becoming entrenched.[5]
Policy prescriptions differ fundamentally if the Phillips curve is flat.
In this case, a large policy impulse is required to move output sufficiently to generate aggregate price effects. It can then be optimal for policy to tolerate moderate deviations of inflation from target, as the cost of closing a small inflation gap relative to the target may exceed the benefits.
This prescription holds in both directions.
When inflation is above the target, a flat Phillips curve would require a sharp rise in policy rates to bring medium-term inflation down from, say, 2.3% to 2%. Such a course of action may imply a substantial rise in unemployment and may thus not be welfare-improving for society at large – a trade-off central banks may face during the last mile of disinflation.[6]
The experience of the 2010s, when inflation was persistently below the target, demonstrates that the argument also holds in the opposite direction.
If bringing inflation up from 1.7% to 2%, for example, requires purchasing a large fraction of outstanding government bonds and making potentially time-inconsistent promises about the future path of interest rates, then the central bank must consider carefully whether the benefits outweigh the costs, such as making losses in the future, market dysfunction, rising wealth inequality, financial instability and threats to its reputation.[7]
The role of inflation expectations
However, the ability to tolerate moderate deviations of inflation from target critically hinges on a firm anchoring of inflation expectations – that is, a low sensitivity of inflation expectations to realised inflation.
If inflation expectations are well-anchored, policymakers can tolerate moderate deviations from target, as fluctuations in inflation tend to fade away. If, however, inflation expectations are at risk of unanchoring, central banks should act forcefully.[8]
There are two challenges to this strategy.
One is that the anchoring of inflation expectations is endogenous. Central banks themselves can cause an unanchoring if inaction in the face of price shocks is perceived as weakening its commitment to securing price stability.[9]
History shows that it can be costly to reestablish the credibility of the nominal anchor once it has been lost. This is also because inflation expectations are path-dependent. Research shows that the experience of high inflation may raise the sensitivity of inflation expectations to new inflation surprises.[10]
The other challenge is that different measures of inflation expectations often yield different results (Slide 3). As such, robust trends cannot easily be identified in real time, much like the slope of the Phillips curve.[11]
Measures of inflation expectations can even point in opposite directions. Research from the early days of the pandemic showed that most consumers expected the pandemic to raise prices, contrary to the views held by professional forecasters at the time.[12]
State-dependent pricing and tight labour markets can explain steeper Phillips curve and post-pandemic inflation surge
The recent period of high inflation illustrates how sensitive policy conclusions can be to the assessment of the slope of the Phillips curve and to measures of inflation expectations that central banks use in their analysis.
Two key theories have been proposed to explain the post-pandemic inflation surge.[13]
The first relates to firms’ price-setting behaviour.
Standard New Keynesian models assume that the probability of firms resetting their prices is constant over time. This is a fair description of aggregate price movements when inflation is low and aggregate shocks are small (Slide 4).
However, the past few years have demonstrated that this “linear” relationship breaks down in the face of large shocks.[14] When marginal costs increase rapidly and threaten to erode profit margins, firms tend to raise their prices more frequently. As a result, the Phillips curve steepens.
This feedback loop is strongly asymmetric.[15] It acts as an inflation accelerator when firms face positive demand or adverse cost-push shocks.[16] But it does little to firms’ pricing strategies in the face of disinflationary shocks due to downward price rigidities.
This helps explain why inflation did not fall much when the pandemic broke out but increased sharply after the reopening of our economies (Slide 5).[17]
The second theory relates to the tightness of the labour market.
Downward nominal wage rigidity has been a key factor explaining the “missing deflation” in the aftermath of the global financial crisis.[18] If nominal wages do not fall, or fall only very slowly, firms’ marginal costs change only moderately, and hence disinflationary pressures face a natural lower bound, even if slack is large.
But when the labour market is tight, wages are more flexible as firms outbid each other in securing their desired workforce.
Benigno and Eggertsson show that this channel led to a non-linear inflation surge in the United States whenever the number of job vacancies exceeded the number of unemployed workers (Slide 6).[19] In the euro area, the threshold was lower, but the curve still exhibited strong signs of non-linearity.
Rising near-term inflation expectations may have shifted the Phillips curve up
New research for the United States, however, suggests that the evidence in favour of the second theory is not very robust.
Specifically, the finding of non-linearity depends critically on which measure is used to control for inflation expectations: non-linearity holds when controlling for expectations of professional forecasters, but it disappears once inflation expectations of households and firms are considered.[20]
In other words, it is conceivable that the Phillips curve did not become steeper but rather shifted upwards as inflation expectations rose.[21] Non-linearity has also been rejected recently using a similar approach based on regional data for the euro area.[22]
Moreover, the expectations that are relevant for such an upward shift are not necessarily the longer-term expectations that central banks typically pay most attention to.
These have remained remarkably stable over the past few years (Slide 7).
Rather, inflation expectations over the near term, such as the next 12 months, may be more important in driving macroeconomic outcomes.
Bernanke and Blanchard, for example, show that one-year-ahead inflation expectations explain a significant share of the recent marked rise in nominal wages, and hence inflation, in the United States.[23] Similar evidence has been found for the euro area and other advanced economies.[24]
Again, there appears to be an asymmetry: the risks that the Phillips curve shifts downwards are substantially lower. Research shows that consumers tend to respond more to inflationary than disinflationary news, as households value increases in their purchasing power and as they pay less attention to inflation when it is low.[25]
The impact of tariffs on inflation in the euro area
Understanding the reasons behind the recent inflation surge is not only important from a conceptual perspective. It also matters for setting monetary policy today, as we are once again confronted with historically large shocks.
For central banks, this is a difficult environment to navigate.
Memories of high inflation are still fresh after a long period of sharply rising prices. And just as during the pandemic, there is considerable uncertainty about how firms and households are going to respond to shocks that are largely outside the historical empirical range.
Ultimately, the impact of current shocks on prices and wages, and hence the appropriate monetary policy response, will depend on the shape and location of the Phillips curve.
Monetary policy should focus on the medium term and underlying inflation
Let me illustrate this by looking at the euro area.
Given the lags in policy transmission, the relevant horizon for monetary policy is the medium term. The past few years, however, demonstrated that inflation forecasting at times of large structural shocks is inherently difficult and plagued by large uncertainty.
For this reason, the ECB and other central banks have increasingly turned to a data-dependent approach to monetary policy, where the observed dynamics of underlying inflation and the strength of monetary transmission are used to cross-check the inflation projections.[26]
This approach remains valid today.[27] But data dependence is not in contrast to being forward-looking.
In the current situation, the high level of economic uncertainty, together with the sharp fall in energy prices and a stronger euro exchange rate, will likely dampen headline inflation in the short run, potentially pushing it below our 2% target.
The question is whether these developments provide meaningful signals about the net impact of current shocks on medium-term inflation.
During the pandemic, for example, a strong appreciation of the euro against the US dollar, by nearly 14% over seven months, and a marked decline in energy prices were followed by a historical inflation surge.
Data dependency hence requires examining the potential channels through which current shocks could affect underlying inflation over the medium term.
In the euro area, there are two main forces that could have the size and persistence to pull underlying inflation sustainably away from our 2% medium-term target.
One is fiscal policy, which is set to expand on a scale unseen outside periods of deep economic contraction.
Germany has eased its constitutional debt brake for defence-related spending, and has committed to spending €500 billion, or more than 10% of GDP, on infrastructure and the green transition over the next 12 years. In addition, the European Commission has invited Member States to activate the national escape clause to accommodate increased defence expenditure across the EU.
The impact of these measures on inflation will depend on how they are implemented, especially their impact on the supply side of the economy. But on balance, the fiscal impulse is likely to put upward pressure on underlying inflation over the medium term.
Global fragmentation is the second force that could have a lasting impact on prices and wages.
As we speak, the scale and scope of tariffs, the extent of retaliation as well as how financial markets respond to these developments all remain highly uncertain.
Ongoing negotiations are a sign that mutually beneficial agreements may still be reached. An ideal outcome – the “zero-for-zero” tariff agreement advocated by the European Commission – could even boost growth and employment on both sides of the Atlantic.
However, should these negotiations fail, the euro area will simultaneously face adverse supply and demand shocks, as the EU has announced that it will retaliate against higher tariffs.
Similar to the pandemic, assessing the relative strength of these forces is inherently difficult. Overall, however, there are risks that a lasting and meaningful increase in tariffs will reinforce the upward pressure on underlying inflation arising from higher fiscal spending over the medium term.
To see this, it is useful to look at the factors driving the macroeconomic propagation of tariffs.
Euro area foreign demand may prove resilient, with limited effects on inflation
The severity of the negative demand shock will depend on two factors.
One is the hit to economic activity in the United States and to global demand from raising tariffs across the board. Under the 2 April tariff rates, the United States will face a supply shock of historic proportions. Inflation is poised to rise, real incomes to fall and unemployment to increase. Retaliatory tariffs would weaken the economy further.
So even in the absence of demand reallocation, foreign demand can be expected to decline if there is a broad increase in tariffs. The depth and persistence of this decline will also depend on other policies, such as tax and spending cuts and deregulation.
And it will crucially depend on the final outcome of tariff negotiations, which is likely to be far less severe than the 2 April announcement.
The second factor affecting the severity of the demand shock relates to the degree of demand reallocation – that is, the elasticity of substitution between foreign and domestic products. This elasticity is highly uncertain and varies across industries, products and countries.[28]
However, a robust finding in the literature is that products that are more differentiated tend to be relatively price-inelastic, as they are more difficult to substitute.
This has great relevance for the euro area, where the bulk of exports to the United States comprise pharmaceuticals, machinery, vehicles and chemicals. These goods are typically highly differentiated (Slide 8, left-hand side).
For instance, the supply of machines for producing semiconductors is basically monopolised by one Dutch company. Similarly, banknotes in the United States are overwhelmingly printed using machinery from a single German manufacturer.
These and other machines are not easy to replace in the short run, giving euro area exporters leverage to pass higher costs on to foreign importers and limiting the hit to foreign demand.
In addition, trade diversion may benefit euro area exports.
Should prohibitive tariffs on Chinese imports remain in place, they will measurably raise the euro area’s price competitiveness in the US market. This can be expected to stimulate demand for euro area goods if there are no alternatives in the United States itself, especially as the number of industries in which both Chinese and euro area firms have comparative advantages has increased measurably over the past two decades (Slide 8, right-hand side).[29]
New research corroborates this view.[30] It finds that the euro area stands to win in relative terms from a global trade war, as its net exports to the world will rise rather than fall as global demand is reallocated across the global network, offsetting the hit to domestic consumption.[31]
In other words, for as long as tariffs are not prohibitive to trade and the uncertainty paralysing activity fades, aggregate euro area foreign demand may prove relatively resilient under a range of potential tariff outcomes.
The recent appreciation of the euro does not refute this view.
The euro has gone through two distinct phases since the US presidential election in November last year. It first depreciated in nominal effective terms by 3% until mid-February, before starting to appreciate. So, in net terms, the euro is trading just 2.6% above last year’s average.
In addition, as most exports to the United States are invoiced in US dollars, the pass-through of changes in the exchange rate to import prices tends to be moderate – by recent estimates just about one-fifth.[32] And potential losses in price competitiveness in third countries are in part compensated by lower import costs, as euro area exports have, on average, a large import content.
This price inelasticity is also reflected in recent surveys, with manufacturing firms reporting an expansion in output for the first time in more than two years (Slide 9). Also, fewer firms are reporting falling export orders.
Even if part of these developments may reflect frontloading by firms, it is remarkable how resilient sentiment has remained in the face of the extraordinary increase in economic uncertainty.
Supply shock puts upward pressure on inflation, reinforced by global supply chains
The downward effects on inflation caused by lower demand are likely to be offset, partly or even fully, by the supply shock hitting the euro area through retaliatory tariffs imposed by the EU and other economies.
The strength of this supply shock also depends on two factors.
One is the extent to which firms pass higher tariffs on to consumers.
In the United States, evidence from the 2018 tariff increase suggests that, in most cases, the pass-through to import prices was de facto complete.[33] At the same time, many firms chose to absorb part of the increase in import prices in their profit margins, thereby limiting the increase in consumer price inflation, at least in the short run.[34]
Whether firms will respond similarly to a renewed rise in tariffs in the current environment is uncertain.
On the one hand, the recent appreciation of the euro, if persistent, provides some margin for euro area firms to buffer cost increases from retaliatory tariffs. On the other hand, profit margins have already been squeezed by high wage growth and a sluggish economy, and the post-pandemic inflation surge may have lowered the bar for firms to pass higher costs on to consumers.
Overall, recent surveys of companies in the United States and the euro area suggest that they plan to gradually pass higher tariffs on to consumers over the coming years.[35]
In addition, in order to compensate for the hit to input costs, firms also tend to raise the prices of goods not directly affected by tariffs. There is evidence that retailers broadly adjust price markups even if only a subset of wholesale prices change.[36]
The second, and related, factor determining the strength of the supply shock relates to global value chains.
Unlike during the wave of protectionism in the 1930s, today the dominant share of international trade, about 70%, reflects multinational firms distributing production across countries and along the value chain to minimise costs. In this process, parts and components often cross borders many times.
Prohibitive tariffs between the United States and China are already disrupting supply chains. Shipments of goods are declining, potentially causing future shortages of critical intermediate goods that could reverberate across the world.
While current conditions are very different from those seen during the pandemic, when supply chain disruptions were a main factor driving the surge in inflation, the impact of tariffs is likely to be amplified as the increase in firms’ marginal costs propagates through the production network.
ECB staff analysis shows that, even if the EU does not retaliate, higher production costs transmitted through global value chains could more than offset the disinflationary pressure coming from lower foreign demand, making tariffs inflationary overall (Slide 10, left-hand side).[37]
These effects will become stronger with full retaliation, including intermediate goods. So far, the EU’s retaliatory measures have disproportionately targeted final consumer goods, such as beverages, food and home appliances – precisely to avoid broader cost effects being transmitted through value chains (Slide 10, right-hand side).
But if the trade conflict intensifies, the scale of retaliation will widen and increasingly include intermediate goods, as these account for nearly 70% of euro area imports from the United States.
In other words, retaliatory tariffs on intermediate goods would constitute a much broader cost-push shock for euro area firms, reminiscent of the post-pandemic supply chain disruptions.[38]
It is possible that these effects will be mitigated by China redirecting goods originally destined for the United States towards the euro area and other economies at a discount.
In practice, however, this mitigation channel is likely to be contained. India, for example, has already raised temporary tariffs on China to curb a surge in imports. Similarly, the European Commission has repeatedly clarified that it intends to protect euro area firms against dumping prices should imports from China rise significantly in response to the evolving trade conflict with the United States.[39]
Policy implications
How, then, should the ECB respond to the current shocks?
The lessons from the post-pandemic surge in inflation suggest that, from today’s perspective, the appropriate course of action is to keep rates close to where they are today – that is, firmly in neutral territory.
A “steady hand” policy provides the best insurance against a wide range of potential outcomes. In other words, it is robust to many contingencies.
Specifically, it avoids reacting excessively to volatility in headline inflation at a time when domestic inflation remains sticky and new forces are putting upward pressure on underlying inflation over the medium term. Given lags in policy transmission, an accommodative policy stance could amplify risks to medium-term price stability.
This steady hand policy also avoids overreacting to concerns that tariffs may destabilise inflation expectations once again.
In recent months, households’ short-term inflation expectations have reversed and started rising again. According to the ECB’s Consumer Expectations Survey, expectations for inflation one year ahead increased to 2.9% in March from their trough of 2.4% in September 2024 (Slide 11, left-hand side). Qualitative inflation expectations, as measured by the European Commission, even rose to levels last seen in late 2022 (Slide 11, right-hand side).
Currently, there are no indications that this rise is persistent, or that inflation expectations are at risk of unanchoring.
Hence, we can afford to look through the rise in short-term inflation expectations. This could change if we see clear signs of a strong and front-loaded pass-through of potential tariff increases – something that could bring us back to the steep part of the Phillips curve. So far, however, evidence suggests that firms have notably slowed the frequency with which they revise their prices.
A steady hand policy also addresses risks of a more substantial decline in aggregate demand in response to the trade conflict.
If tight labour markets were the main culprit for the recent steepening of the Phillips curve, risks of a sharp decline in inflation caused by a rise in unemployment are much more moderate today.
The reason for this is that in both the United States and the euro area, the vacancy-to-unemployment ratio has fallen markedly and is now at a level that suggests that labour markets are much more balanced (Slide 12).
We are thus likely to be operating close to, or at, the flat part of the Phillips curve where a change in unemployment has only limited effects on underlying inflation, in stark contrast to the high inflation period.[40]
We would only need to react more forcefully to the tariff shock if we observed a sharp deterioration in labour market conditions or an unanchoring of inflation expectations to the downside.
Both seem unlikely at the current juncture.
Despite the number of vacancies declining, the euro area labour market has proven resilient, with unemployment at a record low. And most measures of medium-term inflation expectations remain tilted to the upside, including those of professional forecasters (Slide 13).
Conclusion
My main message today, and with this I would like to conclude, is therefore simple: now is the time to keep a steady hand.
In the current environment of elevated volatility, the ECB needs to remain focused on the medium term. Given long and variable transmission lags, reacting to short-term developments could result in the peak impact of our policy only unfolding when the current disinflationary forces have passed.
Over the medium term, risks to euro area inflation are likely tilted to the upside, reflecting both the increase in fiscal spending and the risks of renewed cost-push shocks from tariffs propagating through global value chains.
Therefore, from today’s perspective, an accommodative monetary policy stance would be inappropriate, also because recent inflation data suggest that past shocks may unwind more slowly than previously anticipated.
By keeping interest rates near their current levels, we can be confident that monetary policy is neither excessively holding back growth and employment, nor stimulating it. We are thus in a good place to evaluate the likely future evolution of the economy and to take action if risks materialise that threaten price stability.
Thank you.
Haiti: Displaced families grapple with death ‘from the inside’ and out
In March, the family fled the gangs again – this time to Boucan-Carré where Leineda’s treatments were put on hold:
“Sometimes, we suffer from silent illnesses that destroy us from the inside,” Christiana said.
Gangs on the march
In the past few months, armed gangs in Haiti have been expanding their reach beyond Port-au-Prince towards the Centre and Artibonite Departments, displacing around 64,000 from those areas, according to UN estimates.
Humanitarian efforts to reach displaced communities have been disrupted by regional insecurity and funding shortages.
“What we’re seeing on the ground is unimaginable. Communities are being displaced daily, and the images of women and children fleeing for their lives with nothing are heartbreaking,” said Wanja Kaaria, the UN World Food Programme’s (WFP) Haiti director.
Attacks beyond the capital
The assassination of Haiti’s President Jovenel Moïse in 2021 triggered widespread gang violence in the capital Port-au-Prince. Around 85 per cent of the city is now controlled by gangs. Over one million Haitians have been displaced because of this violence.
In recent months, organised crime groups have expanded their attacks into the Centre Department in western Haiti and neighboring Artibonite in northern Haiti.
In late March, one of the gangs attacked Mirebalais, killing at least 15 civilians and leading to a jailbreak of 515 inmates. In late April, gang members attacked the commune of Petite-Rivière in Artibonite, killing dozens and damaging scores of homes.
Other gang attacks have occurred in the suburbs of Port-au-Prince and throughout Centre, including in Hinche, Boucan-Carré and Saut d’Eau.
Navigating humanitarian aid blockages
After these attacks in the Centre and Artibonite Departments, over 64,000 people have been displaced according to estimates from the UN International Organization for Migration (IOM).
“Across Haiti and as we have seen this week in the Centre region especially, children are trapped in a cycle of fear and suffering, reliving the same nightmare day after day. What they need most urgently is an end to the violence,” Geeta Narayan, United Nations Children’s Fund (UNICEF) representative in Haiti, said.
As a result of ongoing gang activity and security conditions in the region, local authorities have had to scale back humanitarian aid deliveries. UN Children’s Fund, UNICEF, has cancelled planned field missions.
This is particularly difficult for displaced families who are fully reliant on this aid. Danise, a mother of two, has been displaced many times – first leaving her home in Jérémie, then being deported from the Dominican Republic, next, fleeing violence in Mirebalais before finally settling in Boucan Carré.
“I barely have anything to give [my children],” Danise said. “I always have to wait for food distributions to feed them…I just want to go home.”
Dozens of people displaced from the Haitian communes of Mirebalais and Saut-d’Eau attend hygiene awareness sessions in Boucan Carré.
Providing relief to displaced communities
In spite of deteriorating security, UN aid teams are working with local partners and departmental authorities to continue providing resources to displaced civilians.
“[Displaced people have had their] lives upended – entire families struggling to access water, healthcare or adequate shelter.”
The Office for the Coordination of Humanitarian Affairs (OCHA) “remains engaged alongside local authorities and partners to strengthen humanitarian action, despite limited resources, and continues to advocate for increased support,” Modibo Traore, OCHA’s Head of Office in Haiti, said.
Across the Centre Department, UNICEF has reached 8,500 people with resources, including six mobile clinics.
“We are scaling up our response in the Centre department, providing critical health care, reaching thousands of children with psychosocial support, safe water and access to education where it’s needed most,” Ms. Narayan said.
WFP is also working in the Centre Department to provide hot meals and food kits to displaced communities and has provided assistance to over 13,100 displaced individuals in this region as of early May.
This is the moment to step up. The future of Haiti depends on the actions we take today
– WFP Country Director Wanja Kaaria
“WFP food assistance offers dignity for families now living with little hope. However, funding constraints are impeding us from responding at scale.” Ms Kaaria said.
WFP estimates that it will need $72.4 million over the next 12 months and UNICEF estimates that it will need $1.2 million over the next six months to deal with the ongoing displacements in Haiti’s Centre Department.
“This is the moment to step up. The future of Haiti depends on the actions we take today,” Ms Kaaria said.
Finding dignity through care
In recent days, young Leineda has begun to receive the treatment she needs for malnutrition at the Boucan Carré site.
“I feel happy today because before, we didn’t have any doctors to examine us or understand our pain,” Christiana said. The presence of the doctors brings back a sense of dignity. It helps us.”
Keeping a steady hand in an unsteady world

Speech by Isabel Schnabel, Member of the Executive Board of the ECB, at Hoover Monetary Policy Conference “Finishing the Job and New Challenges”, Stanford University
Stanford, 10 May 2025
Standard theory of monetary policy rests on a simple premise: a stable relationship between inflation and the output gap. This is the logic behind the Phillips curve, which, in its most common form, relates inflation to a measure of economic slack, expected inflation and supply shocks.[1]
The relationship between output and inflation was already under scrutiny well before the pandemic.
After the global financial crisis of 2008, inflation didn’t fall nearly as much as had been implied by conventional Phillips curve estimates. And once economies around the world recovered and unemployment fell, the bounce-back in inflation fell short of model predictions.
This is why that episode is known as the period of “missing deflation” and “missing inflation”.[2]
The situation changed fundamentally in the aftermath of the pandemic, when the relationship between inflation and the output gap proved to be much stronger than what would have been expected based on historical estimates. We observed a noticeably steeper Phillips curve across advanced economies, including the euro area (Slide 2).[3]
In my remarks today, I would like to draw lessons from the instability of the Phillips curve over the past 20 years for the optimal conduct of monetary policy. I will argue that the evidence of a re-flattening of the Phillips curve after the long period of high inflation suggests that, in the euro area, the most appropriate policy response to the potential risks to price stability arising from fiscal expansion and protectionism is to keep a steady hand and maintain rates close to where they are today – that is, firmly in neutral territory.
Monetary policy and the slope of the Phillips curve
The slope of the Phillips curve has first-order implications for the conduct of monetary policy.
If the curve is steep, as it appeared to be in recent years, monetary policy is highly effective in reducing inflation, with only a limited impact on growth and employment. The smaller “sacrifice ratio” suggests that central banks should react more forcefully to deviations of inflation from target, even when the economy is hit by a supply shock that pushes inflation up and output down.[4]
A steep Phillips curve hence improves the trade-off facing central banks, weakening the case for “looking through”, as forceful policy action minimises the risks of inflation expectations unanchoring and of inflation becoming entrenched.[5]
Policy prescriptions differ fundamentally if the Phillips curve is flat.
In this case, a large policy impulse is required to move output sufficiently to generate aggregate price effects. It can then be optimal for policy to tolerate moderate deviations of inflation from target, as the cost of closing a small inflation gap relative to the target may exceed the benefits.
This prescription holds in both directions.
When inflation is above the target, a flat Phillips curve would require a sharp rise in policy rates to bring medium-term inflation down from, say, 2.3% to 2%. Such a course of action may imply a substantial rise in unemployment and may thus not be welfare-improving for society at large – a trade-off central banks may face during the last mile of disinflation.[6]
The experience of the 2010s, when inflation was persistently below the target, demonstrates that the argument also holds in the opposite direction.
If bringing inflation up from 1.7% to 2%, for example, requires purchasing a large fraction of outstanding government bonds and making potentially time-inconsistent promises about the future path of interest rates, then the central bank must consider carefully whether the benefits outweigh the costs, such as making losses in the future, market dysfunction, rising wealth inequality, financial instability and threats to its reputation.[7]
The role of inflation expectations
However, the ability to tolerate moderate deviations of inflation from target critically hinges on a firm anchoring of inflation expectations – that is, a low sensitivity of inflation expectations to realised inflation.
If inflation expectations are well-anchored, policymakers can tolerate moderate deviations from target, as fluctuations in inflation tend to fade away. If, however, inflation expectations are at risk of unanchoring, central banks should act forcefully.[8]
There are two challenges to this strategy.
One is that the anchoring of inflation expectations is endogenous. Central banks themselves can cause an unanchoring if inaction in the face of price shocks is perceived as weakening its commitment to securing price stability.[9]
History shows that it can be costly to reestablish the credibility of the nominal anchor once it has been lost. This is also because inflation expectations are path-dependent. Research shows that the experience of high inflation may raise the sensitivity of inflation expectations to new inflation surprises.[10]
The other challenge is that different measures of inflation expectations often yield different results (Slide 3). As such, robust trends cannot easily be identified in real time, much like the slope of the Phillips curve.[11]
Measures of inflation expectations can even point in opposite directions. Research from the early days of the pandemic showed that most consumers expected the pandemic to raise prices, contrary to the views held by professional forecasters at the time.[12]
State-dependent pricing and tight labour markets can explain steeper Phillips curve and post-pandemic inflation surge
The recent period of high inflation illustrates how sensitive policy conclusions can be to the assessment of the slope of the Phillips curve and to measures of inflation expectations that central banks use in their analysis.
Two key theories have been proposed to explain the post-pandemic inflation surge.[13]
The first relates to firms’ price-setting behaviour.
Standard New Keynesian models assume that the probability of firms resetting their prices is constant over time. This is a fair description of aggregate price movements when inflation is low and aggregate shocks are small (Slide 4).
However, the past few years have demonstrated that this “linear” relationship breaks down in the face of large shocks.[14] When marginal costs increase rapidly and threaten to erode profit margins, firms tend to raise their prices more frequently. As a result, the Phillips curve steepens.
This feedback loop is strongly asymmetric.[15] It acts as an inflation accelerator when firms face positive demand or adverse cost-push shocks.[16] But it does little to firms’ pricing strategies in the face of disinflationary shocks due to downward price rigidities.
This helps explain why inflation did not fall much when the pandemic broke out but increased sharply after the reopening of our economies (Slide 5).[17]
The second theory relates to the tightness of the labour market.
Downward nominal wage rigidity has been a key factor explaining the “missing deflation” in the aftermath of the global financial crisis.[18] If nominal wages do not fall, or fall only very slowly, firms’ marginal costs change only moderately, and hence disinflationary pressures face a natural lower bound, even if slack is large.
But when the labour market is tight, wages are more flexible as firms outbid each other in securing their desired workforce.
Benigno and Eggertsson show that this channel led to a non-linear inflation surge in the United States whenever the number of job vacancies exceeded the number of unemployed workers (Slide 6).[19] In the euro area, the threshold was lower, but the curve still exhibited strong signs of non-linearity.
Rising near-term inflation expectations may have shifted the Phillips curve up
New research for the United States, however, suggests that the evidence in favour of the second theory is not very robust.
Specifically, the finding of non-linearity depends critically on which measure is used to control for inflation expectations: non-linearity holds when controlling for expectations of professional forecasters, but it disappears once inflation expectations of households and firms are considered.[20]
In other words, it is conceivable that the Phillips curve did not become steeper but rather shifted upwards as inflation expectations rose.[21] Non-linearity has also been rejected recently using a similar approach based on regional data for the euro area.[22]
Moreover, the expectations that are relevant for such an upward shift are not necessarily the longer-term expectations that central banks typically pay most attention to.
These have remained remarkably stable over the past few years (Slide 7).
Rather, inflation expectations over the near term, such as the next 12 months, may be more important in driving macroeconomic outcomes.
Bernanke and Blanchard, for example, show that one-year-ahead inflation expectations explain a significant share of the recent marked rise in nominal wages, and hence inflation, in the United States.[23] Similar evidence has been found for the euro area and other advanced economies.[24]
Again, there appears to be an asymmetry: the risks that the Phillips curve shifts downwards are substantially lower. Research shows that consumers tend to respond more to inflationary than disinflationary news, as households value increases in their purchasing power and as they pay less attention to inflation when it is low.[25]
The impact of tariffs on inflation in the euro area
Understanding the reasons behind the recent inflation surge is not only important from a conceptual perspective. It also matters for setting monetary policy today, as we are once again confronted with historically large shocks.
For central banks, this is a difficult environment to navigate.
Memories of high inflation are still fresh after a long period of sharply rising prices. And just as during the pandemic, there is considerable uncertainty about how firms and households are going to respond to shocks that are largely outside the historical empirical range.
Ultimately, the impact of current shocks on prices and wages, and hence the appropriate monetary policy response, will depend on the shape and location of the Phillips curve.
Monetary policy should focus on the medium term and underlying inflation
Let me illustrate this by looking at the euro area.
Given the lags in policy transmission, the relevant horizon for monetary policy is the medium term. The past few years, however, demonstrated that inflation forecasting at times of large structural shocks is inherently difficult and plagued by large uncertainty.
For this reason, the ECB and other central banks have increasingly turned to a data-dependent approach to monetary policy, where the observed dynamics of underlying inflation and the strength of monetary transmission are used to cross-check the inflation projections.[26]
This approach remains valid today.[27] But data dependence is not in contrast to being forward-looking.
In the current situation, the high level of economic uncertainty, together with the sharp fall in energy prices and a stronger euro exchange rate, will likely dampen headline inflation in the short run, potentially pushing it below our 2% target.
The question is whether these developments provide meaningful signals about the net impact of current shocks on medium-term inflation.
During the pandemic, for example, a strong appreciation of the euro against the US dollar, by nearly 14% over seven months, and a marked decline in energy prices were followed by a historical inflation surge.
Data dependency hence requires examining the potential channels through which current shocks could affect underlying inflation over the medium term.
In the euro area, there are two main forces that could have the size and persistence to pull underlying inflation sustainably away from our 2% medium-term target.
One is fiscal policy, which is set to expand on a scale unseen outside periods of deep economic contraction.
Germany has eased its constitutional debt brake for defence-related spending, and has committed to spending €500 billion, or more than 10% of GDP, on infrastructure and the green transition over the next 12 years. In addition, the European Commission has invited Member States to activate the national escape clause to accommodate increased defence expenditure across the EU.
The impact of these measures on inflation will depend on how they are implemented, especially their impact on the supply side of the economy. But on balance, the fiscal impulse is likely to put upward pressure on underlying inflation over the medium term.
Global fragmentation is the second force that could have a lasting impact on prices and wages.
As we speak, the scale and scope of tariffs, the extent of retaliation as well as how financial markets respond to these developments all remain highly uncertain.
Ongoing negotiations are a sign that mutually beneficial agreements may still be reached. An ideal outcome – the “zero-for-zero” tariff agreement advocated by the European Commission – could even boost growth and employment on both sides of the Atlantic.
However, should these negotiations fail, the euro area will simultaneously face adverse supply and demand shocks, as the EU has announced that it will retaliate against higher tariffs.
Similar to the pandemic, assessing the relative strength of these forces is inherently difficult. Overall, however, there are risks that a lasting and meaningful increase in tariffs will reinforce the upward pressure on underlying inflation arising from higher fiscal spending over the medium term.
To see this, it is useful to look at the factors driving the macroeconomic propagation of tariffs.
Euro area foreign demand may prove resilient, with limited effects on inflation
The severity of the negative demand shock will depend on two factors.
One is the hit to economic activity in the United States and to global demand from raising tariffs across the board. Under the 2 April tariff rates, the United States will face a supply shock of historic proportions. Inflation is poised to rise, real incomes to fall and unemployment to increase. Retaliatory tariffs would weaken the economy further.
So even in the absence of demand reallocation, foreign demand can be expected to decline if there is a broad increase in tariffs. The depth and persistence of this decline will also depend on other policies, such as tax and spending cuts and deregulation.
And it will crucially depend on the final outcome of tariff negotiations, which is likely to be far less severe than the 2 April announcement.
The second factor affecting the severity of the demand shock relates to the degree of demand reallocation – that is, the elasticity of substitution between foreign and domestic products. This elasticity is highly uncertain and varies across industries, products and countries.[28]
However, a robust finding in the literature is that products that are more differentiated tend to be relatively price-inelastic, as they are more difficult to substitute.
This has great relevance for the euro area, where the bulk of exports to the United States comprise pharmaceuticals, machinery, vehicles and chemicals. These goods are typically highly differentiated (Slide 8, left-hand side).
For instance, the supply of machines for producing semiconductors is basically monopolised by one Dutch company. Similarly, banknotes in the United States are overwhelmingly printed using machinery from a single German manufacturer.
These and other machines are not easy to replace in the short run, giving euro area exporters leverage to pass higher costs on to foreign importers and limiting the hit to foreign demand.
In addition, trade diversion may benefit euro area exports.
Should prohibitive tariffs on Chinese imports remain in place, they will measurably raise the euro area’s price competitiveness in the US market. This can be expected to stimulate demand for euro area goods if there are no alternatives in the United States itself, especially as the number of industries in which both Chinese and euro area firms have comparative advantages has increased measurably over the past two decades (Slide 8, right-hand side).[29]
New research corroborates this view.[30] It finds that the euro area stands to win in relative terms from a global trade war, as its net exports to the world will rise rather than fall as global demand is reallocated across the global network, offsetting the hit to domestic consumption.[31]
In other words, for as long as tariffs are not prohibitive to trade and the uncertainty paralysing activity fades, aggregate euro area foreign demand may prove relatively resilient under a range of potential tariff outcomes.
The recent appreciation of the euro does not refute this view.
The euro has gone through two distinct phases since the US presidential election in November last year. It first depreciated in nominal effective terms by 3% until mid-February, before starting to appreciate. So, in net terms, the euro is trading just 2.6% above last year’s average.
In addition, as most exports to the United States are invoiced in US dollars, the pass-through of changes in the exchange rate to import prices tends to be moderate – by recent estimates just about one-fifth.[32] And potential losses in price competitiveness in third countries are in part compensated by lower import costs, as euro area exports have, on average, a large import content.
This price inelasticity is also reflected in recent surveys, with manufacturing firms reporting an expansion in output for the first time in more than two years (Slide 9). Also, fewer firms are reporting falling export orders.
Even if part of these developments may reflect frontloading by firms, it is remarkable how resilient sentiment has remained in the face of the extraordinary increase in economic uncertainty.
Supply shock puts upward pressure on inflation, reinforced by global supply chains
The downward effects on inflation caused by lower demand are likely to be offset, partly or even fully, by the supply shock hitting the euro area through retaliatory tariffs imposed by the EU and other economies.
The strength of this supply shock also depends on two factors.
One is the extent to which firms pass higher tariffs on to consumers.
In the United States, evidence from the 2018 tariff increase suggests that, in most cases, the pass-through to import prices was de facto complete.[33] At the same time, many firms chose to absorb part of the increase in import prices in their profit margins, thereby limiting the increase in consumer price inflation, at least in the short run.[34]
Whether firms will respond similarly to a renewed rise in tariffs in the current environment is uncertain.
On the one hand, the recent appreciation of the euro, if persistent, provides some margin for euro area firms to buffer cost increases from retaliatory tariffs. On the other hand, profit margins have already been squeezed by high wage growth and a sluggish economy, and the post-pandemic inflation surge may have lowered the bar for firms to pass higher costs on to consumers.
Overall, recent surveys of companies in the United States and the euro area suggest that they plan to gradually pass higher tariffs on to consumers over the coming years.[35]
In addition, in order to compensate for the hit to input costs, firms also tend to raise the prices of goods not directly affected by tariffs. There is evidence that retailers broadly adjust price markups even if only a subset of wholesale prices change.[36]
The second, and related, factor determining the strength of the supply shock relates to global value chains.
Unlike during the wave of protectionism in the 1930s, today the dominant share of international trade, about 70%, reflects multinational firms distributing production across countries and along the value chain to minimise costs. In this process, parts and components often cross borders many times.
Prohibitive tariffs between the United States and China are already disrupting supply chains. Shipments of goods are declining, potentially causing future shortages of critical intermediate goods that could reverberate across the world.
While current conditions are very different from those seen during the pandemic, when supply chain disruptions were a main factor driving the surge in inflation, the impact of tariffs is likely to be amplified as the increase in firms’ marginal costs propagates through the production network.
ECB staff analysis shows that, even if the EU does not retaliate, higher production costs transmitted through global value chains could more than offset the disinflationary pressure coming from lower foreign demand, making tariffs inflationary overall (Slide 10, left-hand side).[37]
These effects will become stronger with full retaliation, including intermediate goods. So far, the EU’s retaliatory measures have disproportionately targeted final consumer goods, such as beverages, food and home appliances – precisely to avoid broader cost effects being transmitted through value chains (Slide 10, right-hand side).
But if the trade conflict intensifies, the scale of retaliation will widen and increasingly include intermediate goods, as these account for nearly 70% of euro area imports from the United States.
In other words, retaliatory tariffs on intermediate goods would constitute a much broader cost-push shock for euro area firms, reminiscent of the post-pandemic supply chain disruptions.[38]
It is possible that these effects will be mitigated by China redirecting goods originally destined for the United States towards the euro area and other economies at a discount.
In practice, however, this mitigation channel is likely to be contained. India, for example, has already raised temporary tariffs on China to curb a surge in imports. Similarly, the European Commission has repeatedly clarified that it intends to protect euro area firms against dumping prices should imports from China rise significantly in response to the evolving trade conflict with the United States.[39]
Policy implications
How, then, should the ECB respond to the current shocks?
The lessons from the post-pandemic surge in inflation suggest that, from today’s perspective, the appropriate course of action is to keep rates close to where they are today – that is, firmly in neutral territory.
A “steady hand” policy provides the best insurance against a wide range of potential outcomes. In other words, it is robust to many contingencies.
Specifically, it avoids reacting excessively to volatility in headline inflation at a time when domestic inflation remains sticky and new forces are putting upward pressure on underlying inflation over the medium term. Given lags in policy transmission, an accommodative policy stance could amplify risks to medium-term price stability.
This steady hand policy also avoids overreacting to concerns that tariffs may destabilise inflation expectations once again.
In recent months, households’ short-term inflation expectations have reversed and started rising again. According to the ECB’s Consumer Expectations Survey, expectations for inflation one year ahead increased to 2.9% in March from their trough of 2.4% in September 2024 (Slide 11, left-hand side). Qualitative inflation expectations, as measured by the European Commission, even rose to levels last seen in late 2022 (Slide 11, right-hand side).
Currently, there are no indications that this rise is persistent, or that inflation expectations are at risk of unanchoring.
Hence, we can afford to look through the rise in short-term inflation expectations. This could change if we see clear signs of a strong and front-loaded pass-through of potential tariff increases – something that could bring us back to the steep part of the Phillips curve. So far, however, evidence suggests that firms have notably slowed the frequency with which they revise their prices.
A steady hand policy also addresses risks of a more substantial decline in aggregate demand in response to the trade conflict.
If tight labour markets were the main culprit for the recent steepening of the Phillips curve, risks of a sharp decline in inflation caused by a rise in unemployment are much more moderate today.
The reason for this is that in both the United States and the euro area, the vacancy-to-unemployment ratio has fallen markedly and is now at a level that suggests that labour markets are much more balanced (Slide 12).
We are thus likely to be operating close to, or at, the flat part of the Phillips curve where a change in unemployment has only limited effects on underlying inflation, in stark contrast to the high inflation period.[40]
We would only need to react more forcefully to the tariff shock if we observed a sharp deterioration in labour market conditions or an unanchoring of inflation expectations to the downside.
Both seem unlikely at the current juncture.
Despite the number of vacancies declining, the euro area labour market has proven resilient, with unemployment at a record low. And most measures of medium-term inflation expectations remain tilted to the upside, including those of professional forecasters (Slide 13).
Conclusion
My main message today, and with this I would like to conclude, is therefore simple: now is the time to keep a steady hand.
In the current environment of elevated volatility, the ECB needs to remain focused on the medium term. Given long and variable transmission lags, reacting to short-term developments could result in the peak impact of our policy only unfolding when the current disinflationary forces have passed.
Over the medium term, risks to euro area inflation are likely tilted to the upside, reflecting both the increase in fiscal spending and the risks of renewed cost-push shocks from tariffs propagating through global value chains.
Therefore, from today’s perspective, an accommodative monetary policy stance would be inappropriate, also because recent inflation data suggest that past shocks may unwind more slowly than previously anticipated.
By keeping interest rates near their current levels, we can be confident that monetary policy is neither excessively holding back growth and employment, nor stimulating it. We are thus in a good place to evaluate the likely future evolution of the economy and to take action if risks materialise that threaten price stability.
Thank you.
Statement by the High Representative on behalf of the European Union on call for ceasefire

DISCLAIMER: Information and opinions reproduced in the articles are the ones of those stating them and it is their own responsibility. Publication in The European Times does not automatically means endorsement of the view, but the right to express it.
DISCLAIMER TRANSLATIONS: All articles in this site are published in English. The translated versions are done through an automated process known as neural translations. If in doubt, always refer to the original article. Thank you for understanding.
Costa Rica’s refugee lifeline at breaking point amid funding crisis
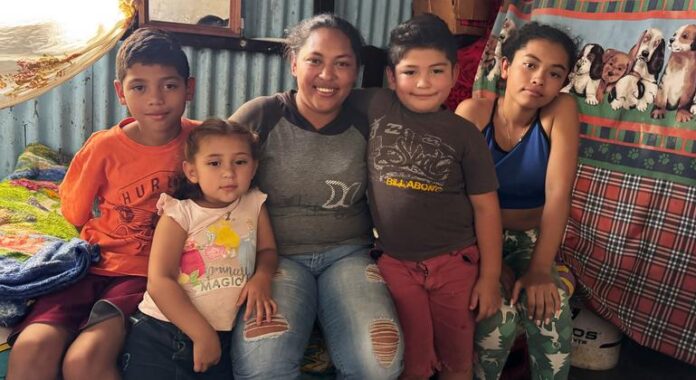
“Without funding, asylum seekers are left in limbo – undocumented, unsupported and increasingly desperate,” said Ruvendrini Menikdiwela, Assistant High Commissioner for Protection.
Her comments follow a 41 per cent budget cut to the UN agency’s operations in the country that have had devastating consequences. “This is not about luxuries; the assistance we’re cutting is critical and lifesaving,” she insisted.
The Central American nation today hosts more than 200,000 refugees and asylum seekers – adding up to nearly four per cent of its population.
More than eight in every 10 are from Nicaragua, fleeing deepening political and social turmoil linked to serious allegations of “systemic repression”, according to independent rights experts reporting to the Human Rights Council.
Despite economic constraints, Costa Rica has continued to offer safety and hope to those escaping persecution, UNHCR said.
Safe spaces at risk
On a recent official tour of Costa Rica, Ms. Menikdiwela described meeting indigenous Miskito women who had fled gender-based violence and established safe spaces, despite language and cultural barriers. “Their courage is humbling,” she said. “But the loss of services threatens everything they’ve tried to rebuild.”
The UN agency has warned that legal support, mental health services, education, job training and child protection initiatives have already been scaled back or suspended.
Many were tailored to vulnerable women and children in remote areas.
No right to a job, school or healthcare
Because of the cuts, the capacity to register new arrivals has plummeted by 77 per cent. But without documentation, refugees cannot legally work, attend school or access healthcare. With over 222,000 claims backlogged, some cases may now take up to seven years to process.
“The Government’s plea to me was simple,” Ms. Menikdiwela said. “‘Help us to help these people.’”
Costa Rica has long played a leadership role in regional and global refugee protection frameworks. But this solidarity is now stretched to breaking point, the UN agency said, in an appeal for $40.4 million to maintain its operations in the country Rica through 2025.
“This is a stark reminder that protection must be backed by resources,” Ms. Menikdiwela warned. “If the international community does not step up, the consequences will be severe – not just for those already in Costa Rica – but for stability in the wider region as well.”
Ukraine: Press remarks by High Representative Kallas following the informal meeting of Foreign Affairs Ministers
Ukraine: Press remarks by High Representative Kallas following the informal meeting of Foreign Affairs Ministers Source link